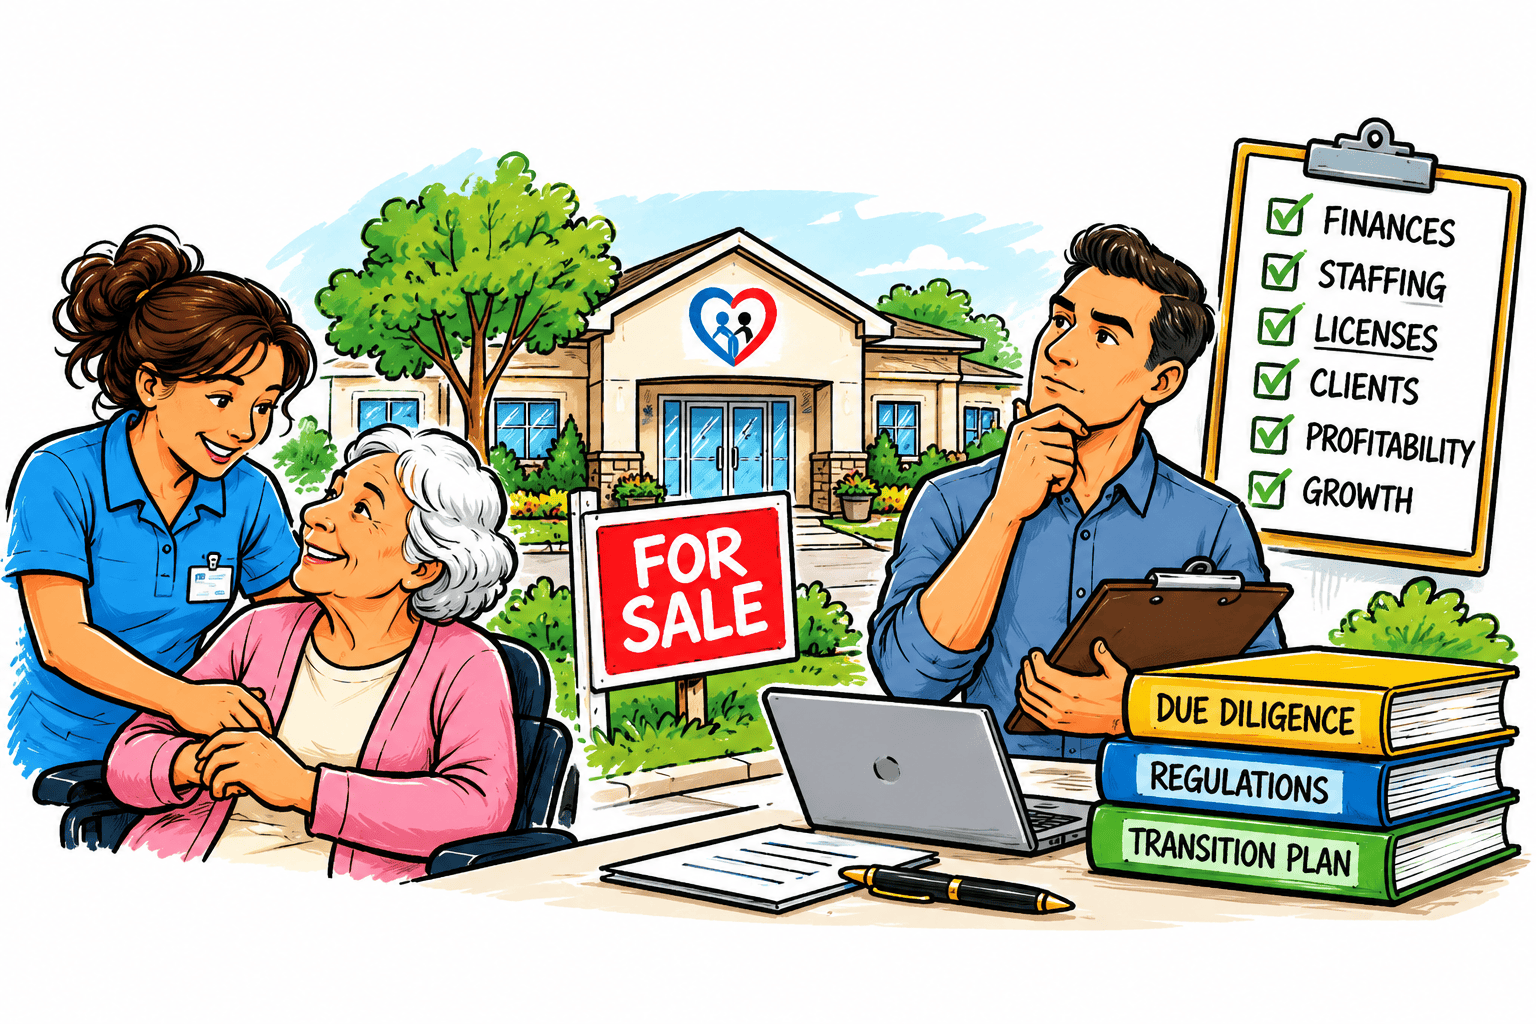
Buying an existing senior care company can look simple on paper. Find an agency with clients, review the numbers, negotiate a price and take over.
Then you start digging.
Who actually provides the care? Are the caregivers employees or contractors? Where do the clients come from? Does one referral source account for half the business? Is the owner personally holding everything together? What happens to the license when ownership changes? Are you buying a company—or buying yourself a demanding full-time job?
Those questions matter because “senior care business” can describe very different businesses.
Before you start comparing asking prices, figure out exactly what you’re trying to buy.
🏠 First, What Kind of Senior Care Business Are You Buying?
Two listings can both say “senior care,” yet have almost nothing in common operationally.
You might encounter:
Non-medical home care
Caregivers typically help seniors with everyday activities such as companionship, meal preparation, transportation and personal assistance.
Home health care
This can involve skilled nursing and other clinical services. Medicare certification, state licensing and healthcare regulations can make an acquisition considerably more complicated.
Residential care homes
Care is provided in a residential setting rather than sending caregivers into clients’ homes.
Assisted living businesses
Now you’re potentially dealing with the operating business, residents, employees, a licensed facility and real estate or a lease.
Senior transportation or companion services
These can have a much different regulatory and financial structure from businesses providing hands-on personal or medical care.
That distinction should come before you start falling in love with a listing.
A business showing $2 million in annual revenue isn’t automatically more attractive than one producing $900,000.
You need to know how that money is being made.
💰 Don’t Buy the Revenue Number
This is probably one of the easiest traps for a first-time buyer.
$1.5 million in annual revenue sounds impressive. But how much of it actually survives after the caregivers, office staff, insurance, payroll taxes, rent, marketing and everything else gets paid?
For smaller owner-operated businesses, buyers frequently encounter Seller’s Discretionary Earnings (SDE).
Larger, more professionally managed businesses are more commonly evaluated using adjusted EBITDA—earnings before interest, taxes, depreciation and amortization, adjusted where appropriate.
Current home-care M&A guidance shows that SDE is commonly used for smaller owner-led agencies while adjusted EBITDA becomes more important as companies grow and develop professional management. Business Broker
Neither number should simply be accepted because it appears on a broker’s listing.
You want to see what created it.
Get underneath the advertised cash flow
Ask for financial records that allow you and your accountant to compare:
Tax returns → Profit-and-loss statements → Bank activity → Payroll → Reported revenue
They should tell a story that makes sense together.
Suppose the seller claims $300,000 in annual owner benefit.
Fine.
Now find out how much work the owner performs.
If the owner handles sales, hiring, scheduling, client complaints and referral relationships—and plans to disappear after closing—you may need to hire one or more people to replace that labor.
Suddenly that $300,000 can look very different.
👀 The Business May Be the Caregivers, Not the Office
A senior care company can have a beautiful website, a polished logo and an impressive client list.
None of those can show up at Mrs. Johnson’s house at 7:00 tomorrow morning.
The caregivers can.
That makes staffing one of the areas worth investigating carefully.
Look at:
- Number of active caregivers
- Employee turnover
- Average length of employment
- Open positions
- Unfilled shifts
- Overtime
- Pay rates
- Recruiting costs
- Background-screening procedures
- Training requirements
- Supervisors and managers who intend to remain
Current industry valuation guidance consistently identifies caregiver retention and staffing stability as important factors affecting the quality and value of a home-care operation.
And don’t stop at:
“We have 75 caregivers.”
Ask how many are actively working.
A database containing 75 names isn’t necessarily a workforce of 75 people.
🚩 One Customer Can Change the Entire Deal
Imagine you’re considering a company producing $1 million in annual revenue.
You discover that one large client relationship generates $280,000 of it.
Now imagine that relationship disappears three months after you buy the company.
That’s a very different acquisition.
This is called customer concentration, and the same thinking applies to referral sources.
A senior care company might receive clients from:
- Hospitals
- Physicians
- Rehabilitation facilities
- Senior communities
- Case managers
- Insurance relationships
- Government programs
- Online advertising
- Local referrals
- Previous clients and their families
You aren’t merely asking:
“Where do the clients come from?”
You’re asking:
“Will they keep coming after the seller leaves?”
If most new business comes because the owner has spent 20 years personally cultivating relationships with three local referral sources, those relationships deserve serious attention during due diligence.
🧾 Find Out Who Actually Pays the Bills
The person receiving care isn’t necessarily the person—or organization—paying for it.
Depending on the type of business, revenue may come from private-pay clients, long-term-care insurance, Medicaid programs, Veterans Affairs-related programs, Medicare in applicable healthcare settings, or other sources.
This is usually called the payer mix.
It matters because different payers can mean different reimbursement rates, billing procedures, collection times and regulatory requirements.
Don’t look only at what the business billed.
Look at what it collected.
A useful question
How long does it normally take this business to turn completed care into money in the bank?
A profitable-looking business can still create a cash-flow headache if payroll is due every two weeks while a meaningful portion of receivables takes much longer to arrive.
⚠️ THE LICENSE QUESTION COMES BEFORE THE CLOSING DATE
This deserves more attention than it usually gets.
If you’re planning to buy a senior care business, do not assume that because the seller is legally operating today, you’ll automatically be able to continue operating tomorrow.
Requirements vary according to the state, type of care, transaction structure and programs involved.
A change in ownership can trigger applications, notifications, approvals or other requirements. State licensing, Medicare enrollment, Medicaid participation and individual contracts can also involve separate processes.
For Medicare-certified home health agencies, the issue can become particularly important.
CMS has rules concerning changes in majority ownership of certain home health agencies, including circumstances where a new Medicare enrollment and certification process may be required.
And there is an especially important 2026 development for buyers to know about.
As of October 2026, CMS has a temporary nationwide enrollment moratorium affecting Home Health Agencies and Hospices. CMS says it applies to initial applications and includes certain non-exempt changes in majority ownership. The moratorium began May 13, 2026, for six months and CMS says it may be extended.
That does not mean every senior care acquisition is prohibited.
It means you shouldn’t assume a transaction structure works until the licensing and enrollment consequences have been checked for that specific business and deal.
This is an area where an attorney experienced in healthcare transactions can earn his or her fee.
🔎 The Seller Is Part of Your Due Diligence Too
You aren’t only investigating a company.
You’re trying to understand how that company functions without the person selling it.
Ask yourself:
What happens Monday morning if the owner doesn’t come in?
If the answer is not much, that’s encouraging.
If the answer is everything stops, investigate further.
Find out whether the owner personally:
✔ Brings in new clients
✔ Recruits caregivers
✔ Creates schedules
✔ Handles billing
✔ Maintains referral relationships
✔ Resolves employee problems
✔ Deals with families
✔ Controls the bank accounts
✔ Holds required qualifications or licenses
✔ Makes virtually every important decision
Owner dependence can affect both the risk of the acquisition and the value buyers place on the business. Current home-care valuation guidance specifically identifies lower owner dependence and management depth as characteristics buyers tend to value.
You don’t necessarily have to reject an owner-dependent company.
You just need to know what you’re actually buying.
📊 Asking Price and Business Value Aren’t the Same Thing
An owner can ask whatever he wants.
That doesn’t establish market value.
Home-care businesses are often evaluated using normalized SDE or adjusted EBITDA, with the appropriate multiple affected by factors such as company size, staffing stability, payer mix, referral concentration, compliance history and owner dependence.
“Senior care businesses sell for X times earnings.”
can get you into trouble.
Consider two agencies producing exactly the same earnings.
Business A
🟢 Experienced manager staying after closing
🟢 Stable caregiver workforce
🟢 Diversified referral sources
🟢 Clean financial records
🟢 Multiple clients
🟢 Seller isn’t essential to daily operations
Business B
🔴 Owner runs everything
🔴 Constant caregiver turnover
🔴 One referral source drives much of the business
🔴 Questionable add-backs
🔴 Messy books
🔴 Compliance problems
Same earnings.
Not the same business.
🧮 Don’t Spend Every Dollar Buying the Company
The purchase price isn’t necessarily the amount of money you’ll need.
You may also need working capital for:
Payroll + insurance + recruiting + marketing + professional fees + deposits + licensing expenses + technology + unexpected repairs or operating costs
And remember the timing problem.
Employees may need to be paid before some customers or payers have paid the company.
A buyer who can afford the down payment but can’t comfortably operate the company afterward may be undercapitalized.
🏦 Can You Finance a Senior Care Acquisition?
Potentially.
Business acquisitions can be financed through combinations of buyer equity, conventional financing, SBA-backed financing, seller financing and other structures depending on the business and borrower.
But financing should never become the justification for paying too much.
A lender approving a transaction doesn’t magically turn it into a good acquisition.
Your question isn’t simply:
“Can I borrow enough to buy this?”
A much better question is:
“After servicing the debt and paying someone to replace anything the seller currently does, does this business still produce enough cash to make the acquisition worthwhile?”
That’s a harder question.
It’s also far more useful.
📂 WHAT I WOULD ASK FOR BEFORE GETTING SERIOUS
Once a business survives your initial screening, the paperwork needs to start backing up the story.
A serious due-diligence review may include:
| Financial | Operations | Legal & Regulatory |
|---|---|---|
| Tax returns | Active client count | Licenses |
| P&L statements | Caregiver roster | Inspection/survey history |
| Balance sheets | Employee turnover | Complaints/violations |
| Bank statements | Payroll records | Litigation |
| Accounts receivable | Referral sources | Insurance |
| Debt obligations | Client concentration | Material contracts |
| Owner add-backs | Management structure | Change-of-ownership requirements |
That’s not an exhaustive due-diligence list.
The exact documents depend heavily on what kind of senior care company you’re buying.
🕵️ A Beautiful Listing Can Still Hide an Ugly Business
Business-for-sale advertisements are advertisements.
Treat them accordingly.
Words such as:
“Turnkey.”
“Established.”
“Highly profitable.”
“Owner retiring.”
“Huge growth potential.”
may be perfectly accurate.
But they’re not evidence.
If a listing says the company has enormous growth potential, ask why the current owner hasn’t captured it.
If it says the owner works only five hours a week, determine who actually performs the other work.
If it says revenue is recurring, inspect client retention.
If it says the company has an excellent reputation, investigate complaints, regulatory history and online reputation.
If it says employees will remain after the sale, don’t treat that as guaranteed.
Verify the attractive parts of the story just as aggressively as you investigate the bad ones.
🤝 The Transition Can Be Worth Negotiating
The seller’s involvement doesn’t necessarily have to end when the money changes hands.
Depending on the business, a transition agreement could have the seller remain available for an agreed period to introduce you to referral partners, explain operating procedures, assist with relationships and help transfer institutional knowledge.
The key word is agreed.
Define what’s expected.
“Seller will help with transition” is vague.
How long?
How many hours?
Doing what?
Will the seller introduce important referral sources?
Will the seller assist with employees?
Will the seller remain available when an operational question arises?
Put important obligations into the actual transaction documents with your attorney rather than relying on a friendly conversation.
🔴 THREE NUMBERS I WOULDN’T IGNORE
When evaluating a potential acquisition, these three numbers can quickly tell you where to dig deeper.
1. Client concentration
How much revenue disappears if the largest client leaves?
2. Referral concentration
How dependent is the company on its largest source of new clients?
3. Owner-adjusted earnings
What does the company earn after accounting for the realistic cost of replacing the seller’s work?
A fourth number is worth adding for care businesses:
Caregiver turnover
Because clients don’t receive care from spreadsheets.
They receive it from people.
The Best Business May Not Be the Biggest One
A smaller senior care company with dependable employees, clean records, diverse clients, healthy margins and an owner who can leave without the place falling apart may be a much more attractive acquisition than a larger operation held together by its founder.
That’s why someone looking to buy a senior care business should resist starting with:
“How much revenue does it make?”
Start with:
What exactly does this company do?
Who makes it work?
Where does its money come from?
What am I actually receiving when ownership changes?
What could disappear when the seller leaves?
And what has to happen legally before I can operate it?
Once those answers hold up, then the asking price becomes interesting.
Because you’re not really buying last year’s revenue.
You’re buying the business’s ability to keep working after the keys are yours.
This article is for general educational purposes and is not legal, tax, accounting, investment, lending or healthcare regulatory advice. Licensing and ownership-transfer requirements vary by jurisdiction and type of senior care business.